Australia’s Card Surcharge Ban 2026: What the RBA’s Landmark Reform Means for Small Business Pricing and Margins
The End of an Era for Card Surcharging
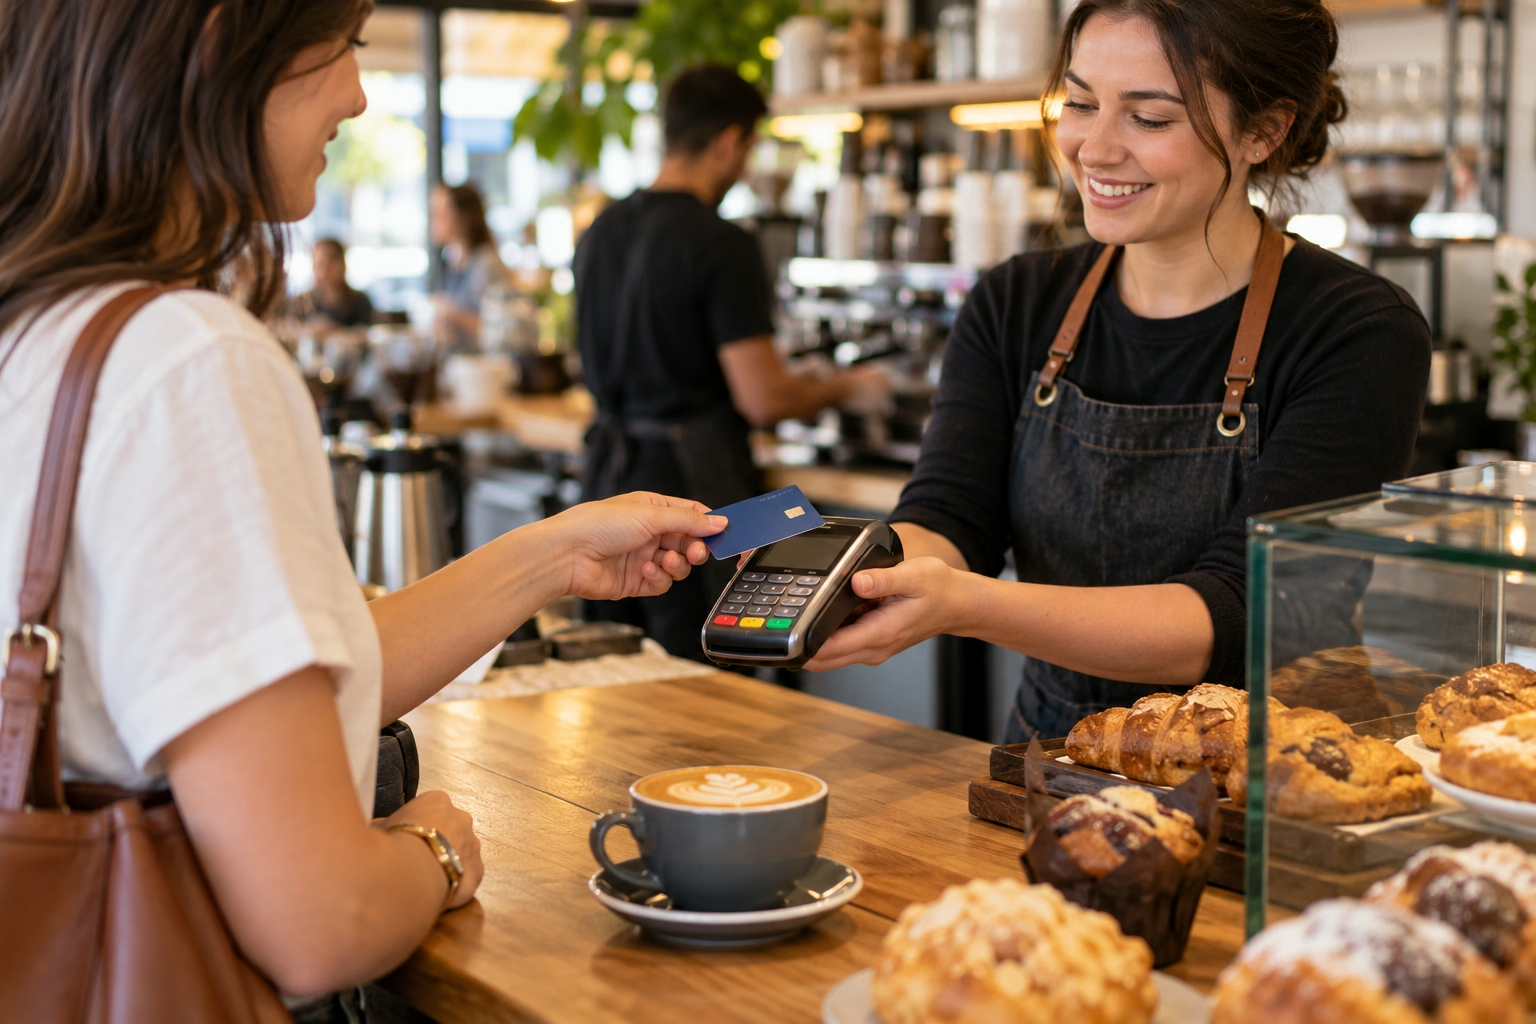
From 1 October 2026, Australian businesses can no longer apply surcharges to card payments. This sweeping reform, announced by the Reserve Bank of Australia (RBA) on 31 March 2026, marks the culmination of a two-decade experiment with payment surcharging that began in 2003. The RBA concluded that surcharging no longer serves its intended purpose of steering consumers toward lower-cost payment methods, as declining cash usage and widespread flat-rate surcharges have rendered the framework ineffective.
The policy shift affects transactions across eftpos, Mastercard, Visa, and American Express networks. American Express, JCB, and UnionPay have also confirmed they will remove surcharging from the same date, extending the reform’s reach beyond the designated card networks.
Understanding the Interchange Fee Reduction
While the surcharge ban captures headlines, the less visible but equally consequential change involves interchange fee caps. The RBA has reduced the maximum interchange fee on Australian-issued consumer credit cards from 0.8 per cent to 0.3 per cent of transaction value. For debit and prepaid cards, the cap has dropped to a maximum of 0.16 per cent or $0.08, down from 0.20 per cent or $0.10.
These reductions are designed to offset the cost burden that businesses will now absorb. The federal government estimates that lower fees will save Australian businesses approximately $910 million annually, with small enterprises expected to benefit disproportionately because they typically pay higher effective rates.
Real-World Impact on Small Business Margins
The practical consequences are already materialising. Ross Surace, co-owner of Lennox Street Deli in Melbourne’s Moonee Ponds, pays more than A$1,000 weekly in card processing fees. With the surcharge option removed, he estimates his business could face an additional A$1,200 to A$1,500 per week in transaction costs, prompting him to raise coffee prices by 50 cents and panini prices by A$1.
For businesses operating on thin margins, the absorption of these costs represents a significant structural adjustment. Cafe operators report that profit margins on a single cup of coffee can be less than 10 cents after accounting for ingredients, wages, EFTPOS fees, and overheads.
Strategic Responses: Price Adjustments and Cash Incentives
Small businesses are adopting varied strategies. Some, like the Mount Gambier bakery that paid $5,785 in card fees last financial year, are encouraging cash payments through signage while acknowledging that cash now represents only 16 per cent of transactions. Others are embedding payment costs directly into shelf prices, a practice the RBA explicitly permits as long as businesses do not misrepresent the nature of the charges.
The Australian Competition and Consumer Commission (ACCC) has clarified that the ban applies only to card payment surcharges. Weekend surcharges, public holiday surcharges, booking fees, and other non-card-related charges remain permissible.
The ATO Dimension and Political Fallout
The reform has generated unexpected political friction. The Australian Taxation Office initially announced it would stop accepting credit cards altogether from 30 November 2026, citing an inability to absorb processing costs within legislated tax liabilities. Labor subsequently intervened to delay this measure until July 2027. Opposition leader Angus Taylor seized on the contradiction, noting that while small businesses are instructed to absorb card costs, the government’s own tax office initially refused to do the same.
What Businesses Should Do Now
The RBA’s reforms also introduce transparency requirements. Card schemes and large acquirers must publish the fees they charge, and merchants will receive standardised cost-of-acceptance information on their statements from April 2027. This data will empower small businesses to negotiate more effectively with payment providers.
For SMEs yet to adjust, the immediate priorities include removing surcharge settings across all payment channels, updating customer-facing materials, and reviewing pricing structures to account for absorbed processing costs. The Australian Small Business and Family Enterprise Ombudsman has been tasked with supporting businesses through this transition.